Home insurance for large acreage works like ordinary homeowners insurance until what happens on the land changes the risk. At 50+ acres, the dividing line is usually activity, not size: farming for profit, leased crop or grazing ground, hunting leases, timber work, employees, heavy equipment and many outbuildings. Once those appear, a standard homeowners policy may exclude them, and a farmowners or ranchowners policy, endorsements and umbrella liability may fit better. Fire-station distance and water supply can also affect availability and price.
Key takeaways
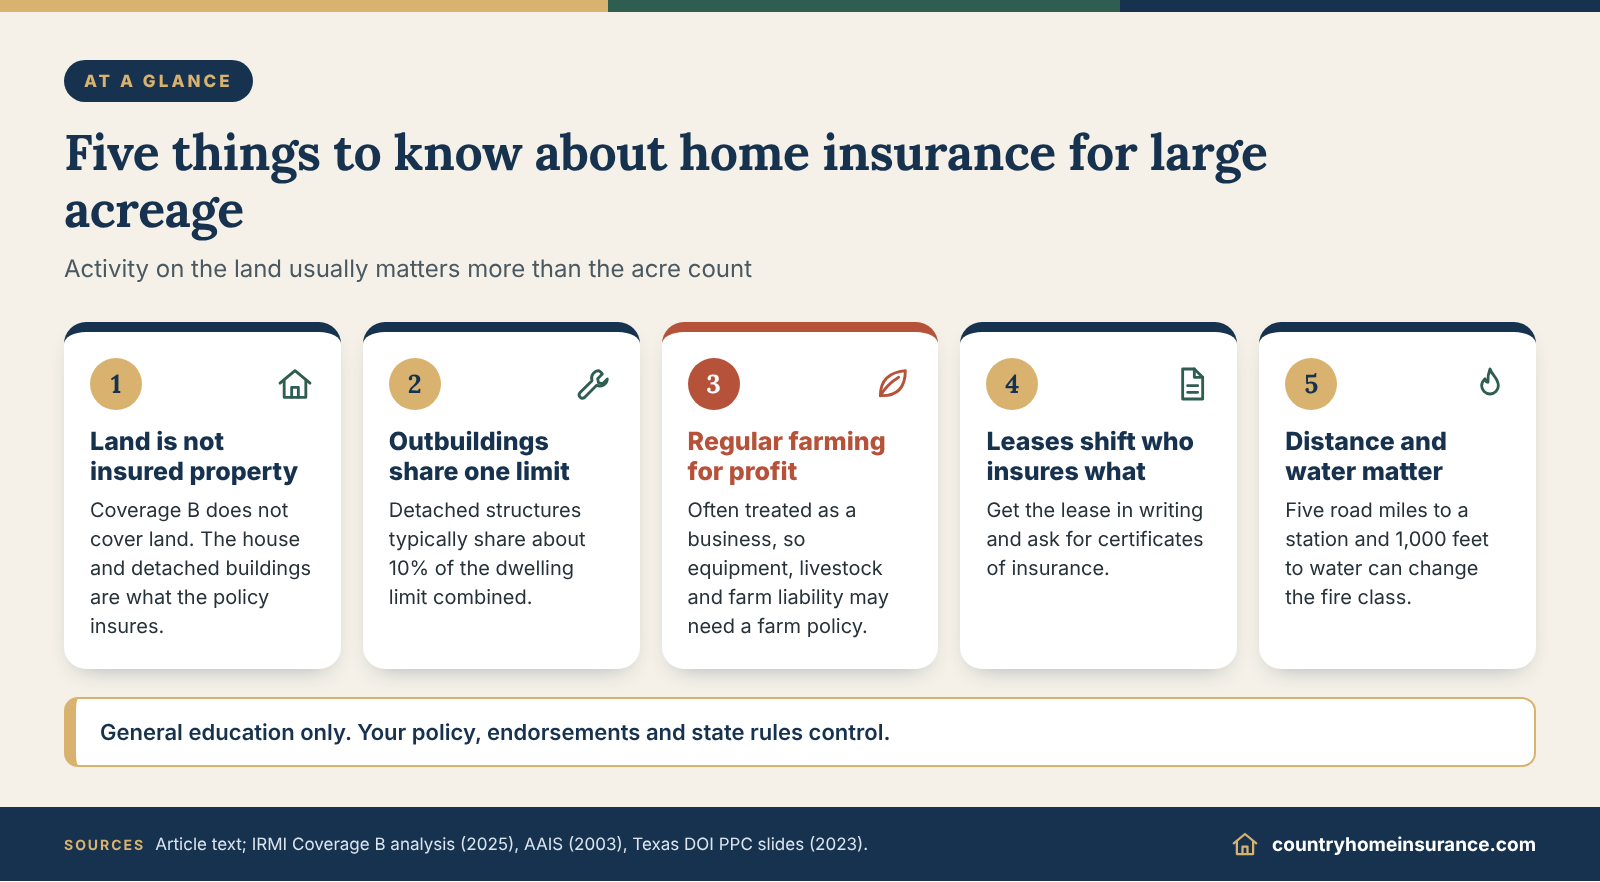
- Land itself is not insured property under a standard homeowners form; the house, detached structures and a few named extras are.
- Homeowners policies typically limit all detached structures combined to about 10% of the dwelling limit, which can be thin on a property with a barn, shop and sheds.
- Regular, for-profit farming is usually treated as a business, so equipment, livestock and farm liability generally need a farm policy or specific endorsements.
- Leasing land to a farmer, a hunting club or a logger shifts who insures what; the written lease and the certificates of insurance matter as much as your own policy.
- Distance to a fire station and a usable water source feed into the fire-protection rating, which insurers may weigh when deciding whether to offer coverage and at what price.
- Wells, septic systems, ponds, private roads and bridges are common gaps; ask about each by name rather than assuming.
Home insurance for large acreage: what changes past 50 acres
Most people searching for home insurance for large acreage want to know one thing: will the policy I already have still work now that I own a lot of land? The honest answer is that it depends on use. This guide focuses on properties of roughly 50 acres and up, where leasing, equipment, employees and distance from help start to matter. If your property is smaller, our guides for 5+ acres, 10+ acres and 20+ acres cover that range, and the broader piece on country homes with acreage covers the basics we skip here.
Acreage versus activity
Land is not the insured item
Under the ISO homeowners form most carriers build on (HO 00 03), the Coverage B “other structures” section covers buildings set apart from the house, but an analysis from the International Risk Management Institute (IRMI) notes that land is not covered. Fifty acres of pasture or woods is therefore not a line item on your policy. What you insure is the home and detached buildings, plus personal property and liability. That is why a quote for 5 acres and a quote for 80 acres can look similar until the insurer asks what you do with the ground.
Where the “farm” label begins
A 2003 article from the American Association of Insurance Services (AAIS) explains that its standard homeowners definition of “business” includes a trade, profession or occupation, including farming, full or part time. The same article says court decisions interpreting the exclusion look for activity that is continuous or regular and aimed at income, although actual profit is not required. ISO wording differs, so treat that as an illustration, not a universal rule. Haying your own field for your own horses sits differently from selling hay every season. The more regular and income-seeking the activity, the more likely the insurer will call it a business. The gray zone at the small end is a separate question that the hobby-scale guides linked near the end of this article address.
What underwriters weigh on a large property
Use of the land
Underwriting is the insurer’s process of deciding whether to offer coverage and at what price. For large parcels, the use of the land comes first: owner-occupied pasture, rented-out cropland, timber, recreational access or livestock each point toward a different product. Disclose them early. A University of Maryland risk-management article (2025) advises telling the insurer about changes in operation size, employees, activities or technology at purchase and renewal, because an undisclosed activity can leave you arguing about coverage after a loss.
Distance, access and water
A property far from a staffed fire station, down a long private lane, with no hydrant, is a different fire risk from a house on a town street. Carriers commonly look at the fire-protection rating for the address and may ask about road surface, gates and on-site water. The fire-protection section below explains the ratings and what a pond can and cannot do.
Home value and outbuilding count
Large acreage often comes with a larger or older home, a guest house, several barns and a shop. Each building needs a value, a use and a condition. For a large residence with significant land and outbuildings but no income operation, see country estate insurance; for the general rural coverage gaps, our rural home insurance guide is the companion piece.
A first look: covered, not covered or depends
Reading the summary table
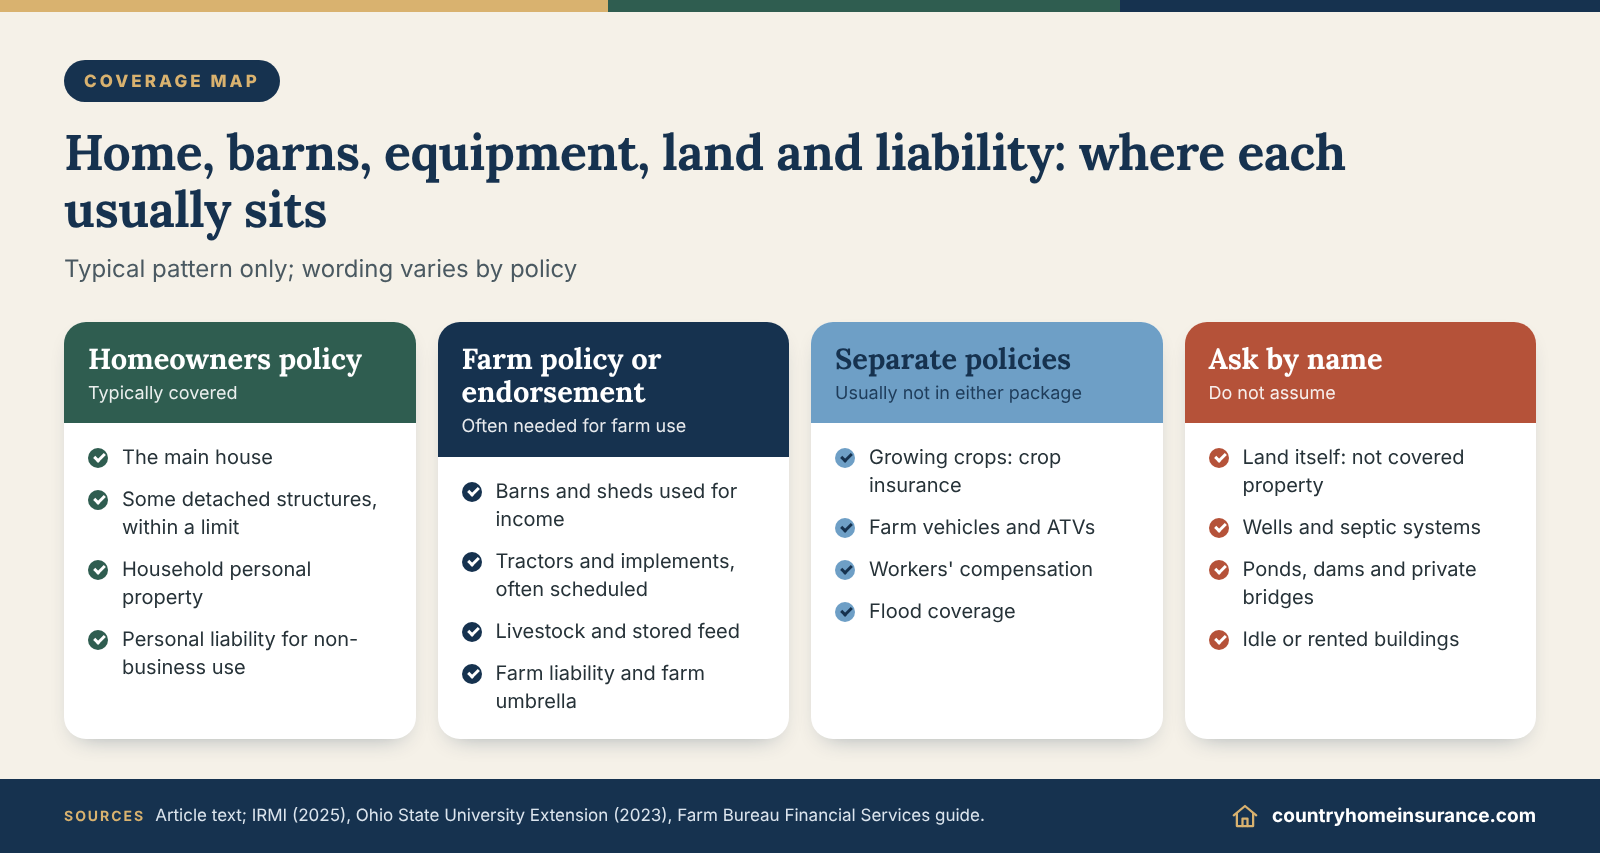
The table below sorts common large-acreage items into three buckets. It describes typical ISO-style homeowners and farm-package behavior, not any single policy. Wording, endorsements, state rules and your declarations page control the result.
Why “depends” is the biggest column
On a large property, many items land in “depends” because the answer turns on use, scheduling or a named endorsement. That is not evasion; it is how the contracts work.
| Item on a 50+ acre property | Typical homeowners (HO-3 style) treatment | Typical farmowners or ranchowners treatment |
|---|---|---|
| The main house | Typically covered, subject to perils, limits and deductible | Typically covered as the farm dwelling, often with similar terms |
| Land, pasture, woods | Typically not covered as property | Typically not covered as property |
| Detached garage, guest house, private barn | Depends: Coverage B, usually about 10% of the dwelling limit, and not if used for business or rented out | Depends: farm structures are usually insured under their own limits and valuation basis |
| Barn or shop used for farming income | Typically not covered under Coverage B when used for business | Typically covered if listed or within the farm-structure limit |
| Tractor, implements, livestock | Depends: farm equipment is commonly treated as business property, so ask what your policy covers | Depends: often scheduled or blanketed, with perils and valuation set by the form |
| Growing crops | Typically not covered | Typically not covered; usually a separate crop insurance product |
| Liability for farming or leasing activity | Depends: business exclusion applies unless an endorsement adds incidental farming | Typically covered within the farm liability limit, with exclusions |
| Trees and shrubs | Depends: limited causes of loss and per-item caps | Depends on the form |
| Wells, septic, ponds, private bridges | Depends: wording, cause of loss and maintenance exclusions | Depends: usually must be named or scheduled |
When a homeowners policy stops fitting a large property
The business exclusion and farming
How policies define business
Homeowners liability and property sections generally exclude business activity. The AAIS article describes farming, full or part time, as part of its standard definition of business, with courts looking at whether the activity is regular and income-seeking. The practical effect: if you board neighbors’ cattle, sell hay or rent pasture, a claim tied to that activity may fall outside the homeowners policy. The exclusion usually attaches to the activity, not to the number of acres.
Incidental farming endorsements
Some carriers offer an endorsement that adds back liability for small-scale farming that is incidental to living on the property. ISO’s homeowners rule manual, in a North Carolina edition effective in 2018 and posted by that state’s Department of Insurance, describes endorsement HO 24 72, “Incidental Farming Personal Liability,” as available when farming is incidental to the home’s use as a dwelling and farm income is not the insured’s primary income. It can apply on the residence premises or at specified locations used for grazing animals or garden space. The same manual lists a separate form, HO 24 73, “Farmers Personal Liability,” for an insured who has a farm away from the residence when farming is not the primary occupation, and it excludes farms whose main purpose is processing commodities for sale and incorporated farms. Carriers file their own versions and rules differ by state, so ask your agent whether your insurer offers either one, under what name, and whether your acreage and activities qualify.
Where the line gets argued
IRMI’s Coverage B analysis summarizes court decisions that turned on whether a building was really used for business. In one Louisiana case a barn holding old farm equipment was covered because the insurer did not prove business use; in another, a farming operation long treated as a business for tax purposes lost the argument. Tax filings, advertising and income records can all be used as evidence, so keep your own records consistent with how you describe the property to the insurer.
Coverage B and the outbuilding gap
The 10 percent limit across many structures
Coverage B, other structures, is typically set at 10% of the Coverage A dwelling limit (Coverage A is the amount insuring the house itself), and IRMI describes it as a blanket limit for all detached structures combined. On a $400,000 dwelling limit that would be $40,000 total (an illustration, not a quote). A barn, a shop and two sheds can use that up with one fire.
Business-use and rented structures
IRMI also notes that Coverage B excludes structures used for business, structures used to store business property, and structures rented or held for rental to someone other than a tenant of the dwelling, with a carve-out for a structure rented solely as a private garage. A tenant house or a rented machine shed is therefore not automatically a homeowners item.
Raising the limit
The same analysis says the limit can be increased by an endorsement (ISO HO 04 48, Other Structures Increased Limits) but not reduced below 10%. Ask whether your insurer offers it, what it costs, and whether it lets you list specific buildings at stated values.
Land, trees and fences
Trees and shrubs on a wooded tract
If part of your acreage is timber or windbreak, know how little a homeowners policy usually pays for trees. The Maryland Insurance Administration says coverage for trees, shrubs and plants is limited to certain causes such as fire, lightning or vandalism, that damage from snow, ice or wind is generally not covered, and that payment is generally capped at 5% of Coverage A with a $500 limit per item. Removal of a fallen tree is typically paid at $500 to $1,000 per event, however many trees come down. If you manage a stand of timber for income, ask your agent in writing whether it is treated differently from household landscaping.
Fences and gates
Miles of fence are common on large acreage. Ask whether fencing and gates are covered under your homeowners policy, whether a farm policy would insure them only if scheduled, and whether electronic gates and entrance structures need a separate endorsement. Get the answer in writing, because fencing coverage can change when you switch from one policy type to another.
Pasture improvements
Drainage tile, irrigation lines, ponds and cleared fields are land improvements, not buildings, and the Coverage B wording IRMI analyzes excludes land itself. Ask whether any of these can be insured, under which coverage part, and with what limit, and keep the written answer with your policy.
Farmowners and ranchowners policies: how they differ
How a farm package is built
Property side: house, farm buildings, farm personal property
A farmowners-ranchowners policy is a package that typically insures the farmhouse and household contents along with farm structures and farm personal property, plus liability. An Ohio State University Extension article (2023) says a typical farm policy often covers farm assets and household personal property under one policy, usually at lower cost than separate policies, and that vehicles are generally not included. It splits farm property into personal farm property, such as machinery, grain and livestock, and farm structures. Ask how each class of property is valued and whether each has its own limit.
Liability side: premises, operations, products
Farm liability generally covers bodily injury and property damage from accidents tied to the farm operation, plus the cost of defending claims, according to the OSU article. Ask whether products sold from the farm, such as produce, fall within the policy. Coverage is not unlimited: a University of Maryland article (2025) lists commonly excluded items such as nuisance claims, environmental violations including chemical spraying and manure spreading, wayward livestock or trespass claims, agritourism, boarding, farmers-market sales, non-farm work and custom farm work. It notes that endorsements and umbrella policies can add coverage in some of these areas.
Basic, broad and special causes of loss
The OSU article explains three levels. Basic covers named perils such as fire, lightning, windstorm or hail, explosion and vandalism. Broad adds more named perils, including falling objects, weight of ice and snow, and accidental water damage. Special covers everything except listed exclusions and costs more. A single farm policy can mix levels, for example special on machinery and broad on other property.
Valuation, scheduling and coinsurance
Blanket versus scheduled
Blanket coverage puts a class of property, such as all unscheduled farm equipment, under one limit. Scheduled coverage lists an item, such as a combine, individually with its own limit. Blanket suits a changing inventory; scheduling avoids arguments over whether a specific high-value item was adequately insured. Ask which of your machines must be scheduled to be covered at all.
Actual cash value versus replacement cost
Actual cash value (ACV) is replacement cost minus depreciation; replacement cost (RCV) pays to rebuild or replace without that subtraction, within limits. On an older barn, the gap between the two bases can be large, so ask which basis applies to each building and each machine, and whether replacement cost can be added by endorsement.
Coinsurance, with a hypothetical example
Coinsurance is a clause requiring you to insure a stated percentage of a building’s value or accept a reduced payment.
Hypothetical example: A machine shed is worth $250,000 to rebuild, and the policy has an 80% coinsurance clause, so $200,000 is required. The owner carries $150,000, and a covered fire causes a $40,000 loss. The simple formula pays $150,000 ÷ $200,000 × $40,000 = $30,000 before the deductible. These figures are illustrative only; your policy’s clause, valuation and deductible control.
What farm policies usually leave to other policies
Growing crops
Standing crops generally sit outside the property portion of a farm package; the OSU article lists machinery, grain and livestock as farm personal property, not growing crops. The U.S. Department of Agriculture’s Risk Management Agency says crop insurance is handled through crop insurance agents and approved insurance providers, and tells policyholders to contact their crop insurance agent to file a notice of loss when crops are damaged. If you lease out cropland, the lease should say who buys crop coverage.
Vehicles and workers’ compensation
Vehicles are generally not part of a farm package, according to the OSU article, so farm trucks, ATVs and trailers typically need their own coverage; ask your agent how each is handled. Employee injuries run through workers’ compensation where required. A Farm Bureau Financial Services guide says that helpers such as relatives or friends who work for a day can create exposure, and that the definition of employee may be broader than owners expect.
Livestock deaths and special losses
Livestock coverage varies by form and by animal. Ask what perils apply to each animal group, whether death from disease or theft is covered, whether a mortality endorsement is available, and whether veterinary costs are included or excluded.
Leasing land for crops, grazing, timber or hunting
Crop and grazing leases
Who carries what, by lease type
A Farm Bureau Financial Services page notes that nearly 40% of U.S. farmland is rented or leased, citing USDA figures, and that the lease determines who covers what. It summarizes lease types from Iowa State University: in a fixed cash lease the tenant pays a set rent per acre and generally controls production; in a flexible cash lease rent depends on the tenant’s profits; in a crop share lease the landowner receives part of the crop and likely insures the buildings and dwelling; in a custom farming contract the operator supplies equipment and labor for a fixed per-acre payment and the landowner pays the other expenses. None of that is automatic; it should be written into your lease.
What to require from a tenant
A Land for Good guide (2018) says the lease should require the tenant to carry farm liability insurance naming the landowner as an additional insured, because a standard homeowners policy generally does not cover commercial farming on a private owner’s land. It recommends getting a certificate of insurance from the tenant’s agent that describes the leased property, and notes the landowner can also ask to see the policy itself. It cites $1,000,000 per occurrence and $2,000,000 aggregate as a commonly required minimum at the time, and advises both parties to confirm appropriate limits with their agents. Also ask your agent whether the tenant’s policy should address vehicles, hired equipment, workers and any non-farm activity such as a farm stand.
Your own policy as the landlord
The same guide says being an additional insured on the tenant’s policy may be enough when paired with your homeowners policy, but some agents recommend separate landowner coverage because sharing one policy limit can leave less money in a claim. It also says a residence rented to a tenant usually needs additional property coverage. Its suggested options include a homeowners policy with an incidental farm and animal liability endorsement, a farm liability policy, or a commercial lessor’s risk (landlord liability) policy added to a retained homeowners policy.
| Arrangement | Landowner usually handles | Tenant or user usually handles |
|---|---|---|
| Cash lease for crops or pasture | Depends: dwelling and building property, lessor’s liability, being named additional insured | Depends: farm liability, equipment, vehicles, workers’ compensation, crop insurance |
| Crop share lease | Depends: the owner likely insures buildings and dwelling under a crop share lease, per a Farm Bureau Financial Services summary of Iowa State material | Depends: equipment, liability and any shared crop coverage per the lease |
| Hunting lease | Depends: your own liability limits and notice to your insurer | Typically a liability policy naming the landowner as additional insured, as the University of Maryland bulletin’s sample lease uses |
| Timber sale or logging | Depends: certificates for workers’ compensation and liability before work begins | Depends: New York guidance from the Catskill Forest Association says a logger in a lump-sum sale generally carries his own workers’ compensation, but state rules differ |
Hunting and recreational leases
Recreational-use statutes vary by state
Many states have recreational-use statutes that limit a landowner’s duty to people using land for recreation, but details differ, and fees are where they diverge. A University of Maryland Extension bulletin (revised 2008) says Maryland’s protection depends on there being no “charge”; charging a fee takes the owner outside the statute. New York’s General Obligations Law section 9-103 removes its protection where permission was granted for consideration (payment), other than payments from state or federal government, and Catskill Forest Association guidance says hunting-lease rent probably counts. Ohio’s statute defines a “recreational user” in a way that excludes lease payments or fees paid to the owner of privately owned land, and an Ohio State University Extension article (2023) says a hunting lease payment therefore keeps the protection while other hunting fees generally defeat it. The same lease can be treated differently from one state to the next, so a local attorney should confirm yours.
Fee-based access and specialty coverage
The Maryland bulletin says free access is often covered under a conventional homeowners or farm policy, to be confirmed with your insurer, while fee-based access takes the owner outside the statute, treats paying users as invitees and usually calls for specialty hunting or recreation insurance. It advises raising your liability limit to at least $1 million if recreationalists use the property often, notes that the extra coverage is usually inexpensive, and suggests that the club or lessee carry its own policy naming the landowner, with the sample season lease requiring a certificate of at least $1,000,000. It is a 2008 document, so use it for the framework, not for current prices.
Managing many hunters
The Ohio State article suggests designated parking areas and set hunting periods when multiple hunters use a property, partly because reasonable steps to manage hunters reduce the chance of a claim that the landowner acted recklessly. Written agreements covering permitted uses, inspection duties and indemnity are another common tool in the Catskill guidance, which recommends a simple agreement under which the user accepts the property as-is and carries their own insurance.
Timber and logging
Lump-sum sales and workers’ compensation
The Catskill Forest Association guidance, written for New York landowners, says a lump-sum timber sale generally relieves the landowner of workers’ compensation requirements because the logger is working for himself, not the landowner. State rules and the facts of the arrangement differ, so confirm with an attorney or your state workers’ compensation agency before relying on that.
Certificates, not promises
The same guidance recommends asking anyone working on your property for certificates showing policy limits and expiration dates, and notes that a workers’ compensation certificate is separate from a liability certificate. If a logger has neither, pause the job and talk to your agent; a short-term policy may be an option.
Equipment, outbuildings and multiple structures
Valuing a barn, shop or machine shed
Get a builder’s estimate
Valuing barns and ranch buildings is difficult, and the owner ultimately chooses the limit, so get estimates from local builders or a regular contractor. Pole barns, steel buildings and post-frame shops have different rebuild costs from stick-built houses. Ask the builder for a rebuild figure that includes demolition and debris removal, and give the same number to the insurer.
Keep a building schedule
For each structure, list age, size, construction, roof type, use, and whether anything is stored or housed inside. A schedule helps you spot which building is the real exposure and gives the insurer something concrete. It is also the first document you will want after a loss.
Mixed-use buildings
A shop that houses family vehicles, hobby tools and a few farm implements is a classic mixed-use building. Under the Coverage B wording IRMI summarizes, storing business property in a detached structure can matter. Tell the insurer what the building really holds, and ask in writing how it will be classified.
Machinery, tools and contents
Tractors and implements
A lawnmower used on your own yard is ordinarily household property, while a tractor used in farming is more likely to be treated as farm property. Ask whether tractors and implements are covered under your homeowners policy at all, whether a farm policy requires them to be scheduled, and whether borrowed or rented implements are covered and for how much.
Breakdown, electronics and GPS
The Farm Bureau Financial Services guide says equipment breakdown coverage can protect against electrical or mechanical failure, that GPS systems and computers used in farm operations may be covered by farm insurance but often are not covered on a homeowners policy, and that farm and ranch operations interruption can replace lost income when an income-producing building can no longer operate. These are add-ons; they are not automatic.
Fuel, chemicals and pollution
The Farm Bureau guide lists fertilizers and pesticides as farm property to check on your policy; ask the same about stored fuel. On the liability side, the University of Maryland article says chemical spraying and manure spreading are often excluded because fines are hard for insurers to value. Ask the underwriter whether your policy has a pollution or chemical-drift exclusion and whether any endorsement is available for your operation.
Livestock and stored feed
Animals under farm forms
As noted earlier, livestock coverage varies by form and animal group. Ask whether animals can be scheduled at an agreed value. Keep photos, tag numbers and purchase records.
Hay, grain and harvested crops in storage
Growing crops are a separate product, but harvested feed raises its own questions. Ask whether hay and grain in storage are covered, against which causes of loss, whether stored feed has a per-location limit, and whether that limit changes seasonally.
Liability and umbrella needs on a working or open property
Who can get hurt on 50+ acres
Visitors, guests and trespassers
The University of Maryland article (2025) outlines that the duty owed varies with the visitor’s status: trespassers and bare licensees such as a hunter are owed the least, invitees such as paying customers the most, and recreational guests invited at no charge may be covered by a statute that removes the duty to make premises safe (Maryland’s, in that article). Those categories come from state law and differ by state. More land means more people, including hunters, neighbors, delivery drivers, contractors and teenagers on ATVs.
Agritourism, boarding and roadside sales
The same article says some insurers decline agritourism, and lists farmers-market sales, boarding dogs or horses, non-farm work such as snow removal or landscaping, and custom farm work among the activities that are commonly excluded. A Farm Bureau Financial Services guide recommends confirming that farm liability coverage extends to activities such as corn mazes, pumpkin patches and U-pick operations, whether year-round or seasonal. If you sell produce from a roadside stand, ask whether products sold are within the policy.
Animals, vehicles and equipment
Horses, bulls and guard dogs, ATVs and farm equipment on public roads all create exposure. The University of Maryland article notes that road accidents are usually covered, but you should ask whether a vehicle counts as part of the farm business. The Farm Bureau guide says farm trucks should carry their own comprehensive, collision and liability coverage and that ATVs should be confirmed as covered.
Employees and contractors
When workers’ compensation enters the picture
Workers’ compensation rules for agricultural workers vary by state, and the Farm Bureau guide says the definition of employee may be broader than owners expect, even for relatives or friends who help for a day. A hired hand, seasonal help or relatives paid to work can all change the picture. Ask your state workers’ compensation agency or insurer rather than assuming a small crew is exempt.
Independent contractors
The 2025 University of Maryland article advises getting written proof of an independent contractor’s liability coverage and a contract requiring the contractor to compensate you if their coverage has a problem. A fencing crew, a driller or a tree service on your 80 acres can be a liability exposure for you unless they carry their own insurance.
Umbrella and farm umbrella
What an umbrella sits on
IRMI describes a farm umbrella as a high-limit liability policy that sits above the primary liability coverage from the farmowners policy, personal auto and any other scheduled underlying liability policy, covering bodily injury, property damage and personal injury offenses, and filling some gaps above a retained limit. Read the umbrella’s own exclusions for farming, leasing and business activity rather than assuming it responds to everything the underlying policies do.
How much to think about
A DTN/Progressive Farmer article (2021) quotes an agricultural underwriter who says the umbrella policies he can offer generally cover $1 million to $5 million, and a farm-insurance consultant who calls $1 million of general liability a minimum and suggests considering $1 million of coverage for every $1 million in assets. An American Family Insurance article (2026) says umbrella coverage is often available in $1 million increments, with limits varying by state and eligibility. These are rules of thumb, not recommendations for your situation.
Business exposures and personal umbrellas
A Texas Department of Insurance filing checklist gives an example of how structure can change regulation: including farm umbrella or commercial general liability in a farm and ranch policy would make the filing a commercial multiperil policy in Texas. State treatment varies, so ask how your own umbrella is filed and what it excludes.
Fire protection distance, grass fire and wildfire on large acreage
Protection class and the five-mile line
How the rating works
A public protection classification (PPC) is a 1-to-10 grade of how well a community can fight a structure fire. Slides from the Texas State Fire Marshal’s Office (March 2023) explain that ISO scores fire departments (50 points), water supply (40), emergency communications (10) and community risk reduction (5.5) using its Fire Suppression Rating Schedule. Insurers use PPC at their discretion alongside other factors.
Five road miles and 1,000 feet
The same slides say Class 10 covers areas beyond five road miles of a fire station, and the split-class system looks at whether a property is within five road miles and within 1,000 feet of a creditable water supply. Hauled water may qualify. Verisk’s 2014 announcement introduced Class 10W for properties 5 to 7 road miles from a station that are within 1,000 feet of a creditable water supply. On a long rural lane, a few miles and a few hundred feet can change the class, so ask what class your address carries and when it was last rated.
Career versus volunteer departments
Whether the responding station is career or volunteer is not what the rating measures directly; the Texas slides describe the schedule as scoring fire department resources, water supply, emergency communications and community risk reduction. Ask your insurer how it uses the protection class for your address, and call the department to learn its response area and tanker capacity.
Water supply: ponds, cisterns and dry hydrants
Why a pond may not count
Ask your insurer whether it expects truck access on a paved or gravel lane, a dry hydrant, or central station alarm monitoring. Whether a pond counts as a creditable water supply for the protection rating is a question for the rating bureau or the fire department; the Texas slides say hauled water could qualify, but not automatically. A pond that responding tanker trucks cannot reach is of little help.
A local example of rural water standards
Douglas County, Colorado publishes a local standard for rural water supplies: at least 250 gallons per minute sustained for two hours (a 30,000-gallon cistern minimum), a water source within two miles of travel from any served parcel, a recorded easement for the fire district, and an all-weather access surface rated for 20-ton apparatus. It says it is based in part on NFPA 1142, ISO schedules and the International Fire Code. It applies to new rural developments with four or more residential parcels and does not apply to existing homes. This is one county’s subdivision rule, not an insurance requirement, but it shows what fire districts think about.
Gates, bridges and turnarounds
Fire apparatus is heavy. If your bridge, culvert or gate cannot take a loaded tanker, a responding department may not cross it. Check with the local fire district and put the answer in your file.
Grass fire, ember and wildfire exposure
The first five feet around buildings
A Texas A&M Forest Service Firewise fact sheet (copyright held by IBHS, referencing 2018 tests) says the first five feet around a structure matters most, recommending removing combustible mulch and dead vegetation, keeping gutters clear and favoring non-woody plants. It suggests extending mitigation to about 100 feet or the property line. Apply it to the house, but also to the barn and the shop.
Spacing and fuel on open ground
Tall dry grass, round bales stacked beside buildings and brush along fence lines can carry fire to structures, so consider spacing and mowing around them. Ask whether your carrier publishes mitigation expectations or offers discounts. For wildfire-specific insurance issues, see wildfire nonrenewal and home-hardening documentation.
Nonrenewal and last-resort markets
The NAIC’s wildfire page (updated June 2025) advises homeowners to review their policies to confirm they protect against wildfire-related losses, create defensible space and contact their state insurance commissioner for personalized help. Last-resort markets vary by state. The California FAIR Plan, for example, describes itself as an insurer of last resort and lists farms among the properties served by its commercial policies. Check your own state insurance department for any residual market and what property it accepts.
Wells, septic systems, ponds and private bridges
Wells and septic systems
What a policy may and may not treat as covered
Policy wording on well pumps, pressure tanks, septic tanks and drain fields varies. As a general pattern, sudden physical damage from a covered cause such as fire may be treated differently from wear, deterioration, settling, root intrusion or lack of maintenance, which policies commonly exclude. Ask your agent three questions: is the well house a structure, are underground components covered, and which causes of loss apply? Request the answer in writing.
Maintenance records help your file
Records of upkeep help show a system was cared for. EPA guidance says a typical household septic system should be inspected at least every three years, systems with pumps or float switches about once a year, and tanks are typically pumped every three to five years. For wells, EPA advises annual testing for coliform bacteria, nitrates, total dissolved solids and pH, plus more testing after flooding or equipment repairs. Keep the lab reports with your policy documents.
After a flood
EPA advises staying away from the pump while an area is flooded, not drinking or washing with flooded well water, and having a well contractor clean and disinfect the well before restarting the pump. Whether flood damage to a well is covered depends on your flood coverage; see our guide on whether homeowners insurance covers flood damage.
Ponds, creeks and dams
Liability from water features
Ponds draw swimmers, skaters and fishermen. The visitor-status rules from the University of Maryland materials matter here, and states differ on doctrines such as attractive nuisance; Maryland, per its 2008 bulletin, has not adopted it. Ask your insurer whether a pond or dam raises premiums, requires fencing or signage, or limits liability coverage.
Damage to the pond or dam itself
Dams, spillways and pond banks are land features, and the Coverage B wording IRMI analyzes excludes land itself. List any dam or earthen embankment on your insurer questionnaire and ask directly, in writing, whether damage to it is covered.
Flood and runoff are separate questions
Overflow from a creek or pond is generally a flood question. The Colorado Division of Insurance says basic homeowners insurance does not include protection from flood damage, so flood coverage is a separate policy. Check your flood zone, and ask whether outbuildings are eligible for flood coverage at all.
Private roads, bridges and gates
Weight, width and emergency access
The Douglas County standard cited above requires an all-weather surface supporting 20-ton apparatus. A one-lane plank bridge over a creek may not meet that standard. Ask the fire district what its trucks can cross and whether alternate access exists.
Who is liable on a shared easement
Many large tracts share a lane or easement with neighbors. Ask your agent how your policy treats liability for a shared private road, and have an attorney review any recorded road maintenance agreement, since the answer depends on your state and the agreement.
Electronic gates and entrance structures
Electronic gates, entrance walls, cattle guards and culverts are separate questions: ask whether each is covered and whether any needs a specific endorsement. Photograph each one.
Vacant barns, empty tenant houses and unused secondary structures
How vacancy changes coverage
The 30-day vandalism condition on farm forms
The OSU article says vandalism coverage usually excludes buildings that have been vacant for more than 30 days, and that special coverage likely has a similar vacancy exception. On a farm with several buildings, one idle barn can become a vacancy problem even while the rest of the property is in use. Check whether “vacant” is defined by contents, occupancy or both.
Freezing in unheated buildings
The same article says freezing of plumbing may not be covered in a building that does not maintain heat. A rarely used guest house or bunkhouse with water lines deserves a winterization plan. Ask what the policy requires: heat, drained lines, or inspections.
Homeowners vacancy wording differs
Vacancy rules in homeowners forms differ by form and by whether the building is a dwelling or an outbuilding. Read the vacancy and unoccupancy conditions in your own policy and ask about each secondary building by name.
Handling idle buildings
Seasonal use versus true vacancy
A hunting cabin used in November and a hay barn empty in June are not necessarily vacant in the policy’s sense, but the policy decides. Ask whether seasonal use is acceptable, and whether storing equipment or feed counts as occupancy.
Document inspections
A simple log of periodic visits, with photos and the date, helps if the insurer later questions the building’s status.
Rented tenant houses and outbuildings
As noted, IRMI says Coverage B excludes structures rented to non-tenants of the dwelling, and the Land for Good guide says a residence rented to a tenant typically needs additional property coverage. If you rent a house or shop on the property, do not rely on the owner-occupied policy.
Underwriting questions and cost drivers for large acreage
What an application may ask
Land use, income and animals
Expect questions about total acres, how much is cropped, grazed or wooded, who farms it, whether anyone pays you to use it, and what animals are present. Answer consistently with your tax filings and lease documents.
Buildings, protection and hazards
Expect questions about every structure, its age and use, the fire department and distance to it, hydrants, water sources, alarm monitoring, ponds, ATVs and trampolines or similar hazards. These details often decide eligibility before they affect price.
Changes during the policy year
If you start leasing, hire help, add a stand or open the land to hunters, tell the insurer. The 2025 University of Maryland article specifically advises disclosing changes in operations, employees and activities.
What drives price and eligibility
Cost drivers without a price claim
Published premium averages vary by methodology, state and coverage assumptions, and blending them for 50+ acre properties would mislead, so this guide gives no price range. Ask for quotes built on your own building list. The table below lists drivers that generally push cost or eligibility up or down.
| Factor | Why it matters | What to ask |
|---|---|---|
| Coverage B or farm-structure limit | Typically 10% of dwelling for homeowners; farm structures use separate limits | Can each building be listed with its own value? |
| Valuation basis | Depends: ACV or replacement cost, often differing by building and equipment | Which buildings are ACV and which are RCV? |
| Coinsurance clause | Depends: underinsuring can reduce a partial-loss payment | What percentage applies, and is there an inflation guard? |
| Deductible structure | Depends: may differ by cause of loss, location or coverage part | Is there a separate wind/hail or per-building deductible? |
| Protection class and water supply | Typically affects eligibility and price at the insurer’s discretion | What is my current class and when was it set? |
| Liability limit and umbrella | Depends: umbrellas are commonly sold in $1 million increments; exclusions still apply | What underlying limits are required? |
| Activities and employees | Depends: leasing, hunting, agritourism or workers can change the product | What endorsements are needed for each activity? |
Deductibles and exclusions to read
The deductible is what you pay before coverage responds. Large properties frequently have more than one policy, so you may carry several deductibles. Ask whether wind and hail carry a separate deductible, and whether windstorm or hail is excluded in your area. In Texas, for example, a Department of Insurance checklist says windstorm or hail may be excluded in farm and ranch filings only in designated catastrophe areas and only with the insured’s signed acceptance. Terms differ by state, so read yours closely.
Shopping with a rural-literate agent
Comparing apples to apples
When you gather quotes, put the same buildings, values, deductibles and endorsements on every request, or the numbers are not comparable. Our guide to comparing home insurance quotes covers the mechanics.
What to have ready
A building list, acreage breakdown, lease copies, equipment inventory and photos speed up the process. Our list of information needed for a home insurance quote covers the baseline items.
When one carrier cannot do it all
Sometimes the home sits with one insurer and the farm operation with another, often with a farm-focused agency. That can work, but the policies must not conflict. Ask each agent how the other policy would be treated, and where the dividing line is on shared buildings.
Choosing between homeowners, endorsements and a farm policy
Three hypothetical properties
Wooded 60 acres, no income
Hypothetical example: A couple owns 60 acres of mostly woods with a house, a detached garage and a small shed, and no one pays them for anything. A standard homeowners policy with an increased other-structures limit and a higher liability limit or umbrella may be a reasonable starting point to discuss. They should disclose any recreational use and ask about trees, the shed and the access road.
Leased cropland, 120 acres
Hypothetical example: A retired owner lives on 120 acres, cash-rents 100 to a neighboring farmer and keeps a machine shed. The shed storing the tenant’s equipment and the rent income raise business-use questions. Options to explore include a landlord-oriented or farm liability policy, additional-insured status on the tenant’s policy, and a written lease stating who insures what.
Cattle operation, 200 acres, one hired hand
Hypothetical example: A family runs 80 cows with hay production, equipment, three barns and a part-time employee. This looks like a farmowners or ranchowners policy with scheduled equipment, livestock coverage, workers’ compensation and an umbrella, with crop insurance handled separately. No quote is implied.
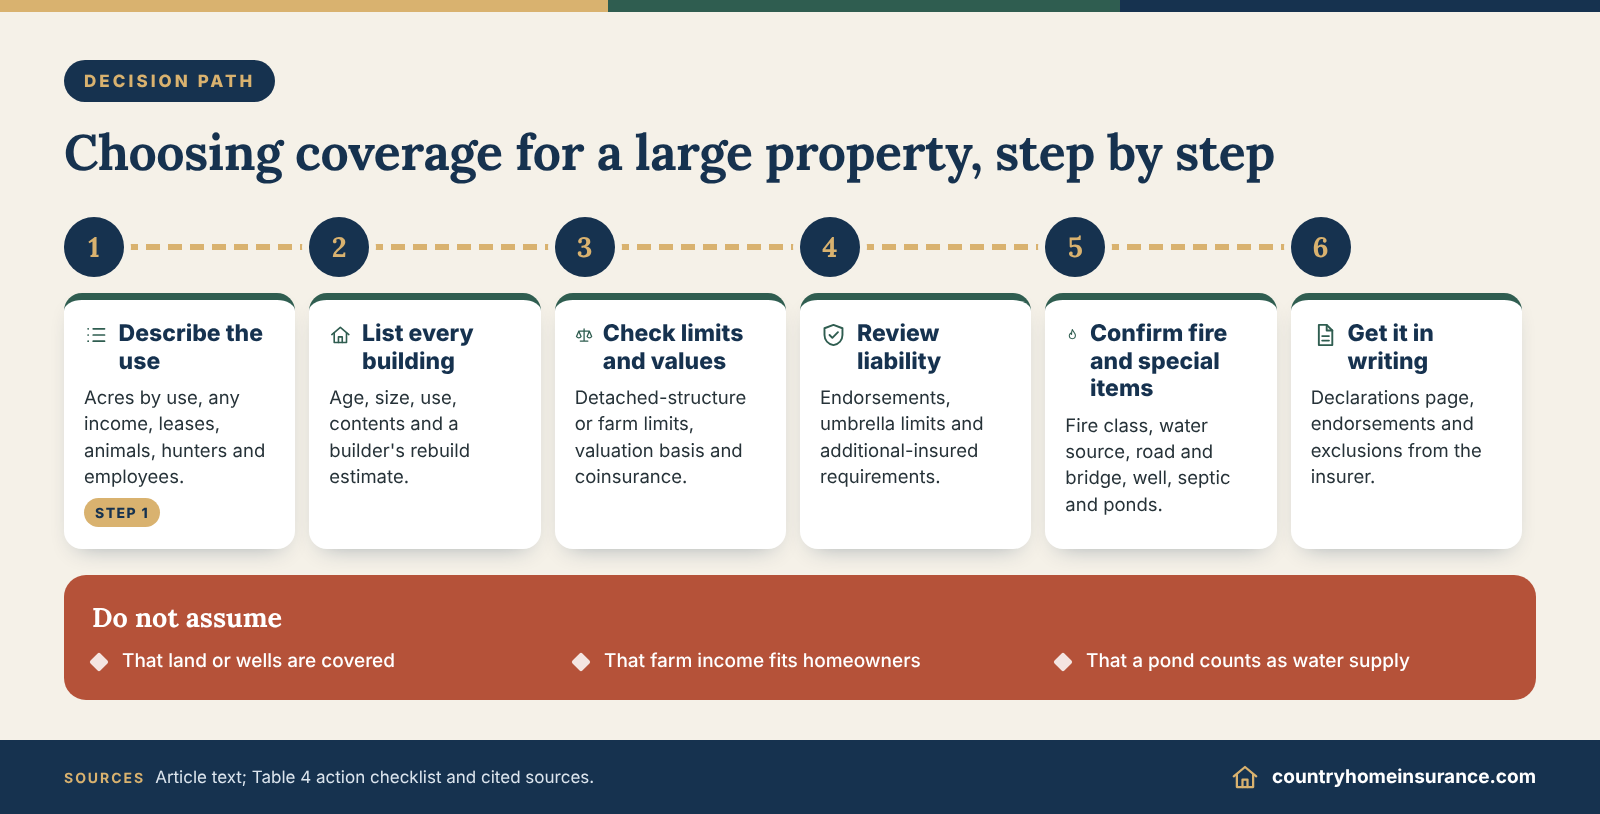
A simple decision path
Questions in order
First, does anyone earn money from the land, directly or by rent? Second, are there employees, contractors or paying visitors? Third, is there equipment or livestock worth more than the homeowners sublimits? Fourth, how many buildings are there, and what do they hold? If you answer yes to the first or third, ask for a farm quote. If you answer yes to the second, address liability and compensation specifically.
Smaller-scale and middle cases
If the operation is small and the honest answer is hobby-scale, see our guides on hobby farm insurance and small farm insurance versus homeowners insurance, which cover that boundary in detail.
| Step | What to verify or document | Who to ask |
|---|---|---|
| 1. Describe use | Acres by use, any income, leases, animals, hunters, employees | Your agent, in writing |
| 2. List buildings | Age, size, construction, use, contents, rebuild estimate | A local builder, then the insurer |
| 3. Check limits | Coverage B or farm-structure limits, valuation, coinsurance | Your agent |
| 4. Schedule equipment | Serial numbers, values, breakdown and mobile-equipment terms | Your agent |
| 5. Review liability | Endorsements, umbrella limits, additional-insured requirements | Agent; attorney for leases |
| 6. Confirm fire protection | PPC class, distance, water source, road and bridge capacity | Fire district; insurer |
| 7. Name the special items | Well, septic, ponds, bridges, gates, fencing, idle buildings | Your agent, item by item |
| 8. Request it in writing | Declarations page, endorsements, exclusions, state rules | Insurer; state Department of Insurance |
Frequently asked questions
Coverage basics
Does 50 acres automatically make me need a farm policy?
No. Size alone does not decide it. What the insurer cares about is use: income, leasing, employees, equipment and livestock. A property of 60 wooded acres with no income may stay on a homeowners policy, while 15 acres with a boarding business may not. Disclose the activities and let the insurer or agent classify them.
Is my land insured?
Generally not as property. IRMI’s analysis of the ISO homeowners form says Coverage B excludes land, including the land under other structures. Buildings and some named items are insured; ask by name about fences, wells, ponds and improvements.
Will a homeowners policy cover my tractor?
It depends. A lawnmower used on your yard is ordinarily household property, but a tractor used in farming is more likely to be treated as farm property that a farm policy covers, often by schedule. Ask your agent how your homeowners policy treats it, and ask for a schedule if you move to a farm policy.
Liability and leasing
Do I need an umbrella?
Many owners of large properties consider one. Sources cited here describe umbrella limits starting at $1 million, often sold in $1 million increments, but the right amount depends on assets, activities and the underlying policies. Ask whether it responds to leasing and business exposures.
Do I need insurance if I lease land to a farmer?
Yes, you generally still need your own coverage, and your tenant should carry liability insurance naming you as additional insured, according to Land for Good. Your homeowners policy may not cover commercial farming on your land, so ask your agent what applies to a landlord.
Does a hunting lease change my insurance?
It can. Fee-based access may remove statutory protection in some states and may need specialty coverage, but not in every state. Notify your insurer before the lease begins and have the lessee name you as additional insured.
Fire, water and special items
How far from a fire station is too far?
There is no single cutoff. PPC Class 10 begins beyond five road miles of a station, and water within 1,000 feet can matter. Carriers decide how to use the rating, so it can help to ask more than one.
Is my well or septic system covered?
It depends on the policy and the cause of loss. Ask by name, get the answer in writing, and keep test and pumping records.
What if my insurer will not renew me?
Ask for the reason in writing, compare other carriers or farm-focused agencies, and contact your state Department of Insurance about your rights and any residual market. Rules vary by state.
Sources
- Ohio State University Extension, CFAES Farm Office — Farm Insurance Policies, Part 1: Understanding the Policy (Robert Moore, 2023-02-02; accessed 2026-10-16)
- IRMI Online — Homeowners Coverage B: Other Structures (analysis of ISO HO 00 03 03 22) (2025; accessed 2026-10-16)
- Maryland Insurance Administration — What to do if a tree falls on your property (undated; accessed 2026-10-16)
- AAIS Coverage Perspective (Robert J. Prahl) — The Business Exclusion: A Frequent Source of Controversy (labeled AAIS 10/03; accessed 2026-10-16)
- Insurance Services Office (ISO), posted by the North Carolina Department of Insurance — Homeowners Policy Program Manual, North Carolina Rules (HO 24 72 and HO 24 73 rules) (edition 10-18, effective 2018-10-01; accessed 2026-10-16)
- University of Maryland, MD Risk Management — Understanding Agricultural Liability: General Liability Insurance (2025-05-06; accessed 2026-10-16)
- University of Maryland Extension — Landowner Liability and Recreational Access (EB357) (revised June 2008; accessed 2026-10-16)
- Ohio Revised Code — Section 1533.18, definitions for recreational user premises law (accessed 2026-10-16)
- New York State Senate — General Obligations Law section 9-103 (recreational use of real property) (accessed 2026-10-16)
- Ohio State University Extension, CFAES Farm Office — Ten legal tips for landowners considering hunting (Peggy Kirk Hall, 2023-11-22; accessed 2026-10-16)
- Catskill Forest Association via Cornell Cooperative Extension — Landowner Liability (Dinnie Sloman; undated; accessed 2026-10-16)
- Land for Good — Liability and Insurance in a Farm Lease (Mike Ghia, 2018; accessed 2026-10-16)
- Farm Bureau Financial Services — Do You Need Insurance on Leased Farmland? (undated; accessed 2026-10-16)
- Farm Bureau Financial Services — The Farm Owner’s Guide to Insurance (undated; accessed 2026-10-16)
- IRMI — Farm umbrella policy (definition) (undated; accessed 2026-10-16)
- DTN Progressive Farmer — Check Your Coverage (Des Keller, 2021-10-31; accessed 2026-10-16)
- American Family Insurance — Farm Insurance for Farmers Renting Land (updated 2026-08-12; accessed 2026-10-16)
- U.S. Department of Agriculture, Risk Management Agency — Crop insurance home page (accessed 2026-10-16)
- Texas Department of Insurance / State Fire Marshal’s Office — Public Protection Classification Oversight (slides) (2023-03-23; accessed 2026-10-16)
- Verisk — New PPC fire protection classes to benefit insurers and communities (2014-04-01; accessed 2026-10-16)
- Douglas County, Colorado — Exhibit C, Water Supplies (local standard for rural fire fighting) (accessed 2026-10-16)
- Texas A&M Forest Service / Firewise — Immediate Noncombustible Zone fact sheet (2025 posting; accessed 2026-10-16)
- National Association of Insurance Commissioners — Wildfires (updated 2025-06-02; accessed 2026-10-16)
- California FAIR Plan Association — Home page and eligibility information (accessed 2026-10-16)
- Texas Department of Insurance — Farm and ranch filing checklist (accessed 2026-10-16)
- U.S. Environmental Protection Agency — How to care for your septic system (accessed 2026-10-16)
- U.S. Environmental Protection Agency — Protect your home’s water (private wells) (accessed 2026-10-16)
- Colorado Division of Insurance — Flood insurance (accessed 2026-10-16)
Important coverage note
Coverage depends on the actual policy, endorsements, exclusions, limits, deductible and cause of loss. State laws and programs vary, and the sources above range from regulators and statutes to extension programs, trade associations and insurer education pages, so confirm current terms. This article is educational information, not legal advice or an insurance contract. For case-specific questions about your acreage, leases or claims, check with your insurer or agent and your state Department of Insurance, and consult an attorney for lease and liability questions.
About the editorial team
This guide was prepared by the countryhomeinsurance.com editorial team as general, educational information for homeowners. We research and summarize publicly available material, including state insurance departments, the NAIC, federal agencies, regulators’ consumer guides and published insurer and industry resources. We draw only on the sources that were available to us when we wrote this guide, and we list them in the Sources section with dates where we could find them.
Insurance rules, rates, products and program terms change, differ by state and by insurer, and can apply differently to your situation. We cannot guarantee that this content is complete, current or free of errors. It is not legal, financial, tax or insurance advice, it is not an offer to sell insurance or a recommendation of any insurer, agent or product, and reading it does not create a professional relationship of any kind.
To the fullest extent permitted by law, countryhomeinsurance.com and its editorial team, authors and contributors exclude all liability for any loss, damage or decision arising from the use of, or reliance on, this content. For questions about your own policy or claim, contact your insurer, a licensed agent or broker, your state Department of Insurance or another qualified professional.
Content created: October 16, 2026